Wells Fargo wins legal battle against former CEO over millions he sought after scandal
Published in Business News
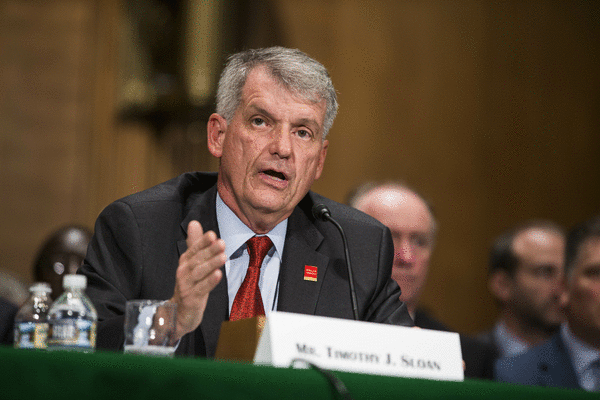
Wells Fargo gained a victory in a legal battle against former CEO Timothy Sloan, who claims the bank owes him $34 million in compensation following his 2019 departure, according to California state court records.
Sloan filed a lawsuit in 2023 against the San Francisco-based bank, which has its largest employment hub in the Charlotte region. According to his complaint, the bank promised him bonuses and multiple stock awards. However, Wells Fargo argued that Sloan is not entitled to the money, according to an April 2024 filing with the Superior Court of California.
On Friday, San Francisco Superior Court Judge Christine Van Aken granted the bank’s motion for summary judgment, ending the lawsuit in the bank’s favor before reaching trial.
The document explaining the judge’s decision contains confidential information and was ordered to remain sealed. Lawyers from both parties were instructed to prepare a redacted version for the public record.
Wells Fargo declined to comment.
Sloan’s attorney, David Lowe, said, “We strongly disagree with the court’s decision, which we believe does not align with the evidence before the court. We are considering our next steps.”
Roots of the lawsuit and sales scandal
Sloan retired in 2019 after a massive sales scandal in which employees created millions of fake customer accounts to meet sales goals.
Attorneys for Wells Fargo raised more than a dozen defenses against Sloan’s claims under California labor laws while denying wrongdoing, The Charlotte Observer previously reported. The bank stated that any alleged labor code violations were made in good faith, based on reasonable grounds and with the understanding that Sloan was aware of the requirements.
Wells Fargo’s attorneys also asserted that the bank “timely paid all amounts due to the plaintiff and did not owe any additional amounts.”
Sloan claimed he was used as a scapegoat for sales practices that resulted in severe regulatory penalties and a congressional hearing over approximately 3.5 million bank and credit card accounts opened without customer permission.
He stated that the problems began before he became CEO and that he attempted to address them prior to retiring from Wells Fargo. The bank elevated him to the top role in 2016 after John Stumpf resigned amid the scandal.
Stumpf was subsequently banned from the banking industry and fined $17.5 million by the Office of the Comptroller of the Currency.
Carrie Tolstedt, Wells Fargo’s former consumer banking chief, was fined $25 million and barred from the industry. A federal judge sentenced her to three years of probation, including six months of home confinement, for misleading investors.
In May 2023, the bank agreed to settle a shareholder class-action lawsuit for $1 billion over claims that it misled investors regarding its regulatory compliance following the scandal.
©2026 The Charlotte Observer. Visit at charlotteobserver.com. Distributed by Tribune Content Agency, LLC.

Comments